One of the most common assumptions I hear about downsizing is this: “If I sell the big house and buy a smaller one, I’ll save money.”
Maybe.
But smaller does not automatically mean cheaper, and a successful move should improve more than the square-footage number on a tax record.
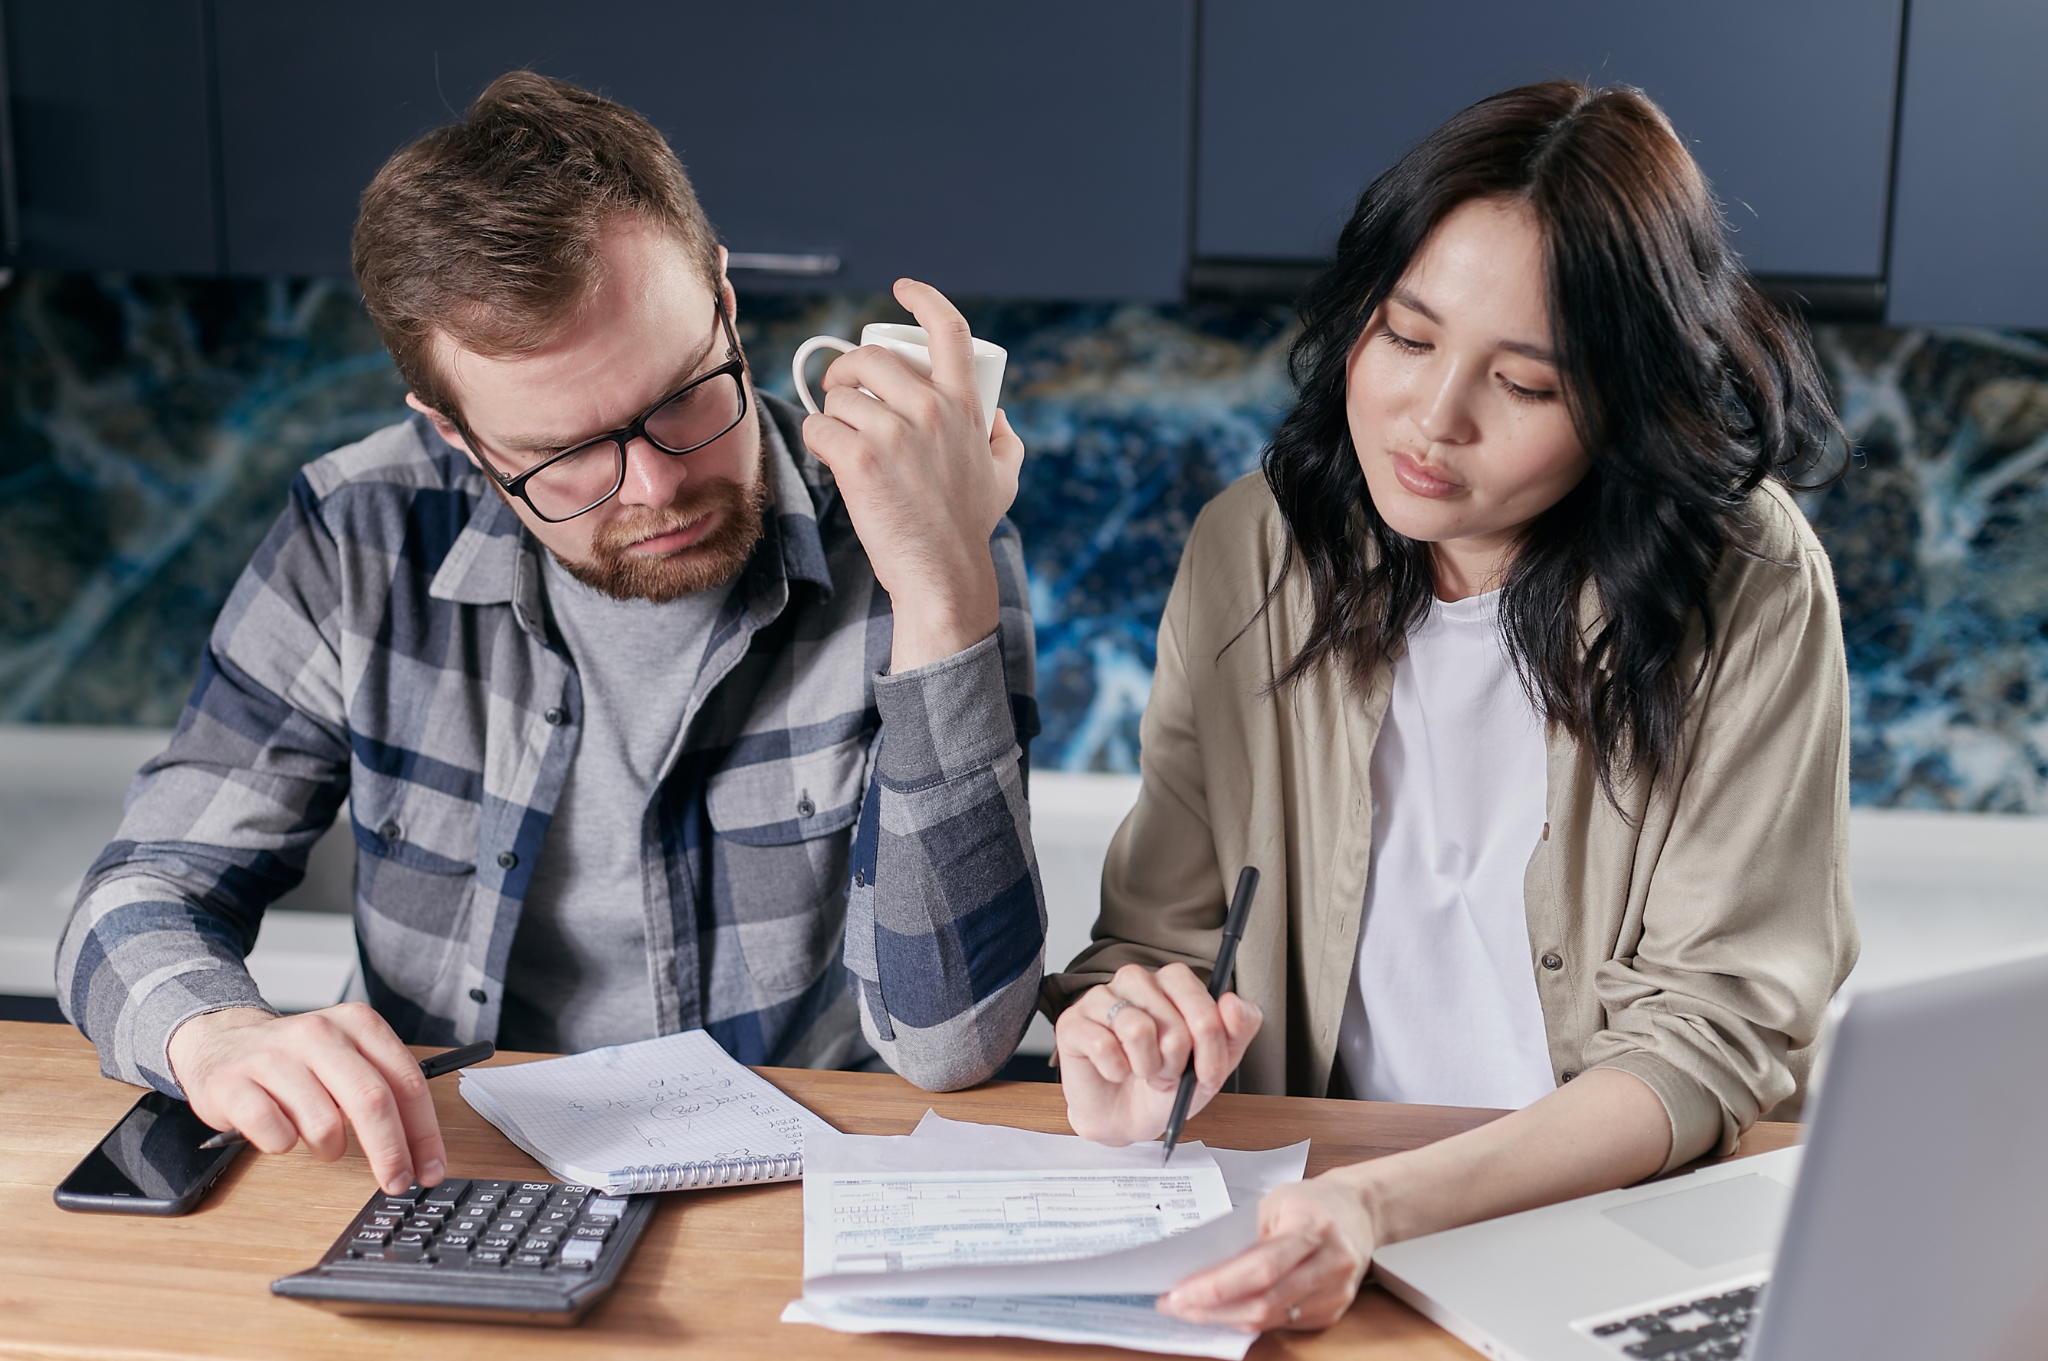
For McKinney seniors who have owned their homes for many years, the decision can involve substantial equity, property taxes, insurance, maintenance, HOA costs, moving expenses and the emotional value of keeping money available for the years ahead.
That is why I prefer the word rightsizing. The goal is not simply to own less house. The goal is to create a housing situation that better fits your finances, energy and next chapter.
Before you put a sign in the yard, here is the math I think you should do.
1. Start with net equity—not your home’s estimated valueIf someone tells you your McKinney home may be worth $600,000, that does not mean you have $600,000 available for the next move.
Start with a realistic probable sale price, then subtract the mortgage balance, expected selling expenses, repairs or preparation costs, moving expenses and any other transaction costs that apply to your situation.
What remains is your estimated net proceeds.
That is the number you can actually plan around.
And in the current market, I would rather estimate conservatively than build a retirement housing plan around the rosiest sale price on the block. McKinney’s August median listing price was $527,125, down 3.72% year over year, and homes sold about 1.07% below asking on average. The city had 2,567 active listings and a median 51 days on market.
Those numbers do not determine what your particular home is worth, but they are a good reminder that pricing needs to be grounded in current comparable sales and current competition.
2. Decide how much equity you actually want tied up in the next homeThis is where many people skip an important question.
Suppose you net $500,000 from the sale. Do you want all $500,000 invested in the next property?
Maybe you do. A mortgage-free home can provide tremendous peace of mind.
But perhaps putting $350,000 into the next home and keeping additional assets liquid better supports your retirement plan. Or perhaps your financial advisor recommends something entirely different based on income, investments, taxes and estate goals.
The Realtor’s job is not to make that financial-planning decision for you. My job is to make sure you recognize that it is a decision.
Do not automatically roll every available dollar into another house simply because that is what you have always done.
3. Compare monthly carrying costs, not just purchase pricesA smaller home can have a surprisingly large monthly carrying cost.
For each housing option, estimate property taxes, homeowners insurance, HOA dues, utilities, lawn care, pool care, repairs and routine maintenance.
Then compare those costs with what you are paying now.
A newer lock-and-leave property with an HOA may cost more per square foot but dramatically reduce maintenance responsibility. An older smaller home may have a lower purchase price but still come with aging HVAC systems, windows, plumbing or a roof that will eventually need attention.
The cheapest house is not necessarily the least expensive house to own.
4. Put a value on deferred maintenanceThis is one of the biggest financial blind spots I see.
A longtime homeowner may say, “My house is paid off, so staying here costs almost nothing.”
Except the house may need exterior painting, foundation work, a new roof, tree maintenance, plumbing repairs, HVAC replacement or bathroom modifications over the next decade.
Those costs do not arrive politely at $200 per month. They tend to show up as $8,000 here and $15,000 there—usually when you would rather be spending money on something more fun.
Create a realistic five- to ten-year maintenance estimate for your current home.
Then do the same for the homes you are considering.
That comparison can change the conversation.
5. Include the one-time cost of movingMoving is not free, even when you are moving into a less expensive home.
Depending on your situation, expenses may include movers, packing help, estate-sale services, junk removal, storage, repairs, painting, cleaning and furnishing the new home.
There can also be costs associated with preparing the existing property for sale.
This is exactly why I do not recommend beginning a downsizing decision by ordering a dumpster and renovating the kitchen.
First determine the plan. Then decide which expenses actually help accomplish it.
6. Ask whether you are buying convenienceNot every benefit belongs neatly in a spreadsheet.
Suppose moving saves only a modest amount each month, but eliminates the pool, upstairs bedrooms, large yard and constant maintenance list.
Is that financially worthwhile?
It might be.
You may be purchasing time, predictability and fewer surprise expenses.
Conversely, if your current home works beautifully, maintenance is manageable and your social network is nearby, moving solely because someone says seniors are “supposed” to downsize may make no sense at all.
There is no prize for owning the fewest square feet after age 70.
7. Run the “stay versus move” comparisonI recommend putting the two choices side by side.
For staying, estimate your current annual housing costs plus realistic future maintenance and any accessibility modifications you expect to need.
For moving, estimate your net sale proceeds, purchase price or rent, transaction and moving costs, annual housing expenses and the amount of equity that would remain available afterward.
Then ask a final question:
What does each choice allow me to do with the rest of my life and money?
That is the part a spreadsheet cannot answer by itself.
8. Do not forget taxes and professional adviceSelling a longtime residence can raise questions about capital gains, exemptions, property-tax rules, estate planning and how proceeds should be invested.
Those issues are personal, and real estate agents should not pretend to be CPAs, attorneys or financial planners.
Before making a major decision, involve the appropriate professionals early enough that their advice can influence the plan—not after the contract is signed.
A coordinated conversation among your Realtor, financial advisor, CPA and estate-planning attorney can prevent the real estate decision from accidentally undermining the financial plan.
9. Give yourself permission to choose the option that works—not the option people expectRightsizing may mean moving from 3,500 square feet to 2,000.
It may mean a one-story home with less maintenance.
It may mean independent living.
It may mean staying exactly where you are and using some of your resources to make the current home easier to manage.
The right answer is the one that fits your finances, your health, your family and the life you actually want.
A simple first step for McKinney seniorsBefore deciding whether to sell, gather four numbers:
- A realistic range for your current home’s value.
- Your estimated net proceeds after selling.
- Your current annual cost of owning and maintaining the home.
- The likely annual cost of the housing alternatives you would seriously consider.
Once those numbers are on paper, the conversation gets much clearer.
You may discover that moving unlocks meaningful equity and reduces your monthly burden.
You may discover that the financial savings are smaller than expected but the lifestyle improvement is enormous.
Or you may discover that staying put is still the best decision.
All three can be good outcomes.
The purpose of planning is not to convince you to sell your home. It is to help you understand your choices before circumstances make the choice for you.
That is what rightsizing should really accomplish.
Kelly Vaughan
The Vaughan Team | Brokered by Keller Williams McKinney
Clarity, compassion, and a plan for what’s next.